Life rarely gives a warning before it throws a financial surprise at you. A sudden hospital bill, a job loss, a car breakdown, or an urgent home repair can arrive in any month. When that happens, the difference between panic and calm is usually one thing: an emergency fund. Yet many Indians, even those with a steady salary, have little set aside for such moments.
The good news is that building an emergency fund is not complicated. It does not need a high income or complicated investments. It needs a clear target, a simple plan, and the discipline to start small and stay consistent.
What Is an Emergency Fund?
An emergency fund is money you keep aside only for unexpected, urgent expenses. It is not your vacation fund, not your festival shopping budget, and not money for a new phone. It is a safety net that protects you from borrowing at high interest rates when life goes wrong.
Without an emergency fund, a ₹50,000 medical bill often lands on a credit card, where interest can quickly turn a one-time problem into months of repayments. With an emergency fund, the same bill is painful but manageable.
How Much Emergency Fund Do You Need?
There is no single number that works for everyone, because monthly expenses differ. Financial planners in India generally suggest keeping three to six months of essential expenses in your emergency fund. If your income is stable, like a government job or a long-term salaried role, three months may be enough. If your income is irregular, like freelancing or running a small business, aim for six months or more.
Here are a few practical examples:
- If your monthly essential expenses are ₹20,000, your target is ₹60,000 to ₹1,20,000.
- If your monthly essential expenses are ₹35,000, your target is ₹1,05,000 to ₹2,10,000.
- If your monthly essential expenses are ₹50,000, your target is ₹1,50,000 to ₹3,00,000.
Essential expenses are the costs you cannot avoid: rent, groceries, bills, transport, school fees, insurance, and loan EMIs. Eating out and shopping do not count. To find your number, look at your bank statements for the last three months and add up the essential spending. That average is your monthly base.
Where Should You Keep Your Emergency Fund?
An emergency fund must be safe and easy to access. That rules out stocks, equity mutual funds, and long lock-in products. Here are the three sensible options most Indians use:
- A separate savings account. This is the simplest choice. Open a second savings account and keep one to two months of expenses here. The money is available instantly through UPI or ATM, which matters in a real emergency.
- A fixed deposit (FD). Keep the remaining part of your fund in a short-term FD, ideally six months to one year, that you can break easily if needed. FDs earn more interest than a savings account, and most banks now allow premature withdrawal through net banking or their app.
- A liquid mutual fund. Liquid funds usually give slightly better returns than a savings account, and money generally reaches your bank account within one working day. Keep only a part of your fund here, because redemption is not instant.
For a ₹1,50,000 fund, you could keep ₹50,000 in a savings account and ₹1,00,000 in an FD. The exact split matters less than the principle: the money should be safe, separate from daily spending, and reachable within a day.
Step-by-Step Plan to Build Your Fund
Step 1: Calculate your monthly essential expenses
Average your last three months of essential spending. Multiply it by three for your minimum target and by six for your comfortable target. The smaller number is your first goal.
Step 2: Start with a small first milestone
A target of ₹1,50,000 can feel impossible when you are starting from zero. So break it down. Your first milestone can be just ₹10,000, or one week’s expenses. Reaching a small goal quickly builds confidence. Then aim for one month of expenses, then three.
Step 3: Automate a fixed amount every month
Set a standing instruction or auto-debit from your salary account to your emergency fund account on the day your salary arrives. At ₹3,000 a month, you will have ₹36,000 in a year, plus interest. The amount matters less than the regularity.
Step 4: Use windfalls to speed things up
Salary bonuses, tax refunds, cashback, or money from selling old items are perfect for your emergency fund. Moving even half of it to the fund does not hurt your lifestyle but moves your goal forward by months.
Step 5: Cut one expense temporarily
Pick one non-essential expense to pause until your fund is complete. It could be ordering food twice a week instead of four times, or skipping one subscription for six months. A saving of ₹1,500 a month becomes ₹18,000 in a year, which is nearly one month of expenses for many families.
Common Mistakes to Avoid
The first mistake is keeping the emergency fund in the same account as daily spending. Keep it in a separate account you do not check every day.
The second mistake is investing the whole fund in the stock market or equity mutual funds for higher returns. Its job is to be there when you need it, even if the market is down that week.
The third mistake is using the fund for planned expenses. A holiday, a new phone, or a wedding are important, but they are not emergencies. They need their own savings plan. Every planned use weakens the safety net.
The fourth mistake is never starting because the target looks too big. A small fund is far better than no fund. Even ₹25,000 can cover a minor hospital visit or a month of rent.
When to Use the Fund, and How to Rebuild It
Use the fund only for genuine emergencies: medical expenses, urgent home or vehicle repairs, or covering essential expenses after a job loss. If you are unsure whether something is an emergency, ask yourself two questions. Is it unexpected? And is it urgent? If the answer to both is yes, use the fund without guilt. That is exactly what it is for.
After using it, rebuilding becomes the priority. Restart the monthly auto-debit, even if the amount is smaller for a while, and direct any extra income to the fund until it is back to your target.
Conclusion
An emergency fund is one of the simplest and most powerful steps in personal finance. It does not require a high salary or expert knowledge. It requires a clear target based on your real expenses, a separate account, and a small automatic saving habit every month. Start with whatever amount you can manage today, even if it is ₹1,000 or ₹2,000. A year from now, you will either have a growing safety net or still be wishing you had started. The best time to start was a year ago; the second best time is today.
Related Reading
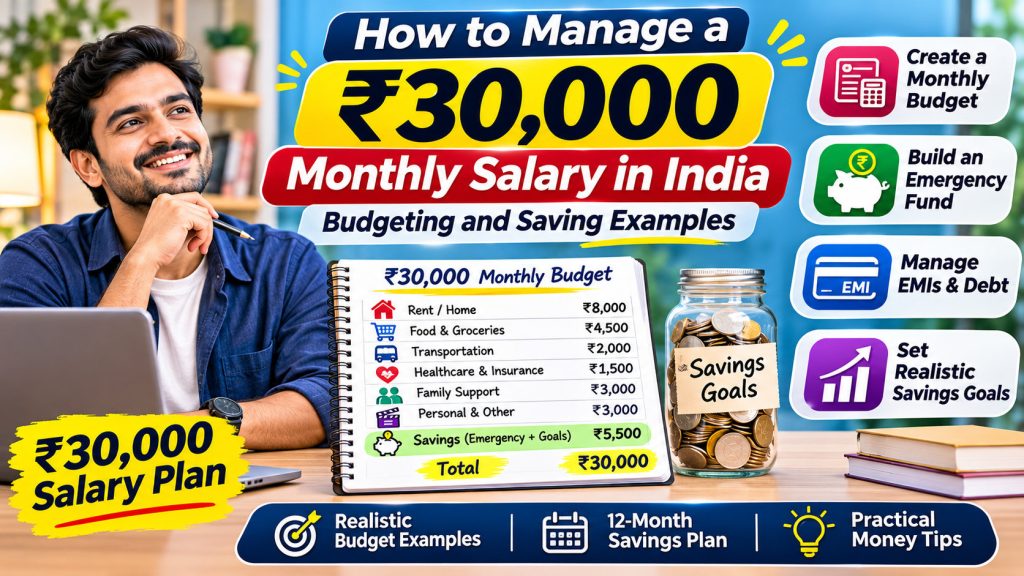
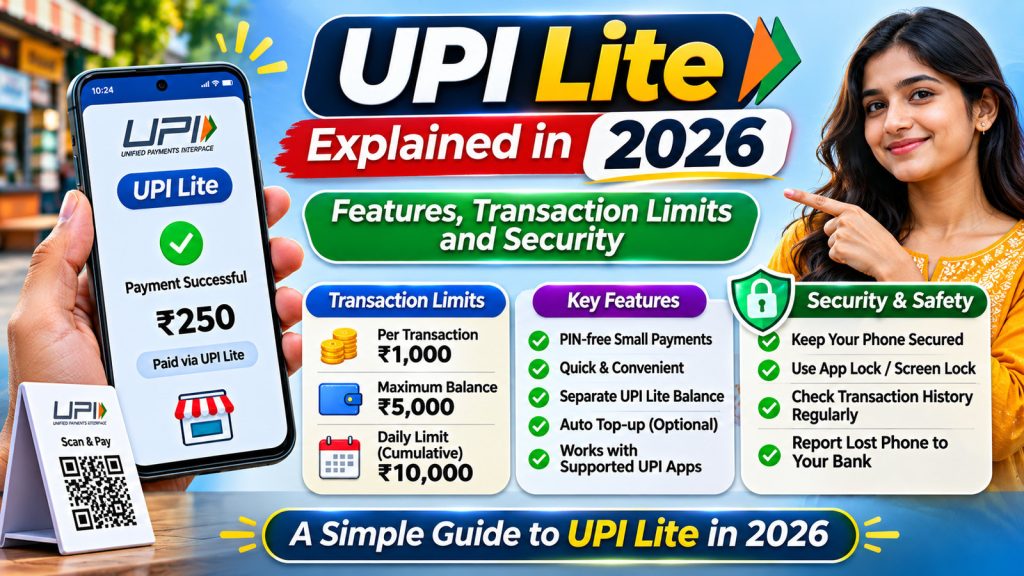
Also read on highlocus: How to Manage a Rs. 30,000 Monthly Salary in India and Income Tax Slabs 2026-27 Explained with Examples. For everyday money, see UPI Lite Explained in 2026.